Fuel Retail Strategy Report: Station Network Scaling in East Africa and the Evolution of Global Forecourt Standards
Rubis network totals and the Conexxus–IFSF governance change require careful separation from investment outcomes.
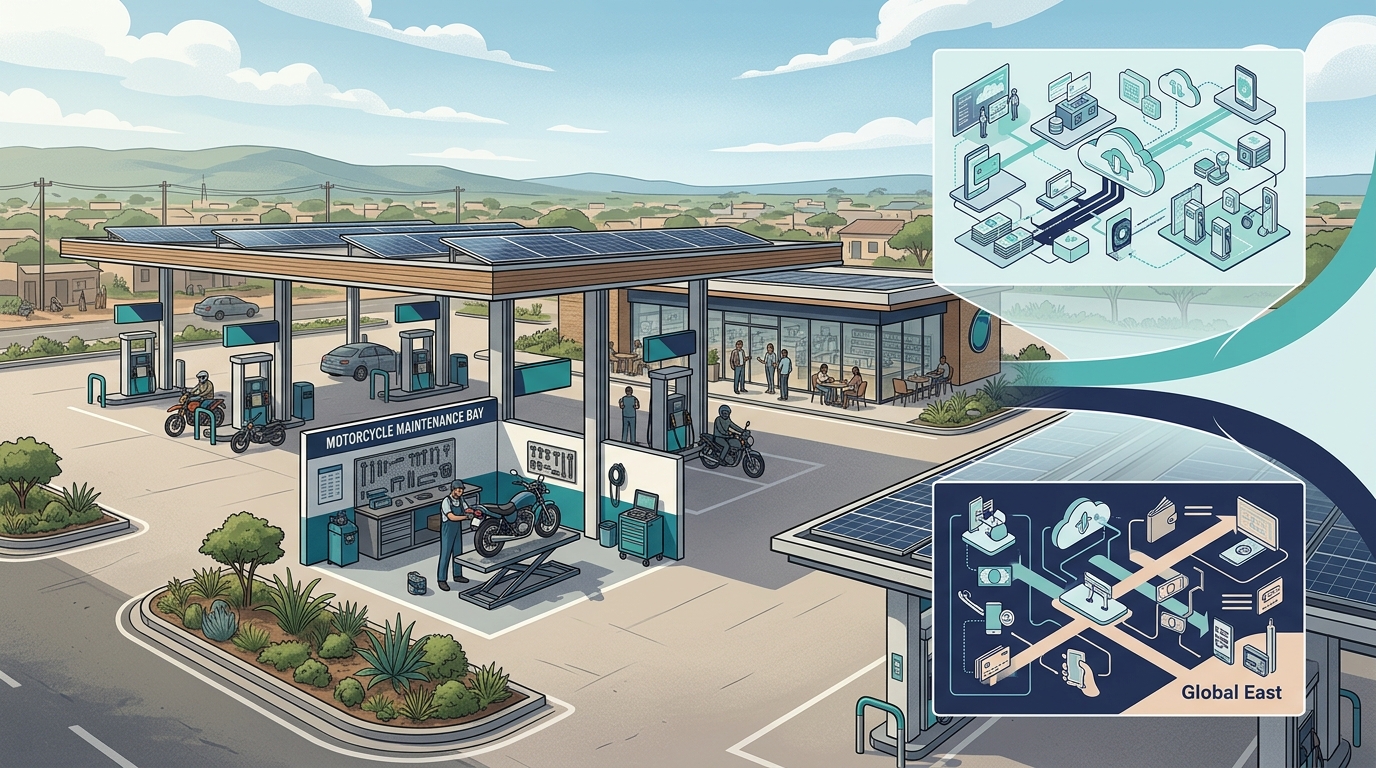
Editorial illustration
Reported network expansion
MobilityPlaza reports that Rubis Uganda opened ten stations in central and western Uganda. The same report gives network totals of 67 rebranded stations, 29 RUBiS Enjoy stores and 18 Castrol service bays, with eight more station conversions planned. These totals should not be described as 29 new stores and 18 new service bays added by the ten-station opening. Rubis Uganda report
The report also describes services aimed at motorcycle users and improvements to amenities. It establishes the reported offer and company direction, not the contribution or return achieved at each location. These are dated reporting figures, not a live independently audited estate inventory.
Operator analysis: evaluate the actual catchment
Before transferring that approach to another market, identify the customers a location can realistically serve. Review access, local vehicle types, competitor services, opening hours and demand by daypart. A site’s position on a busy road is a starting point for evaluation, not proof of an attractive return.
Treat non-fuel services as individual operating propositions. Include training, equipment, replenishment, servicing and customer support in the cost model. Measure contribution with the relevant costs included rather than labelling every additional service high-margin.
For expansion, compare the proposed offer with the organisation’s ability to maintain it. A narrower service consistently delivered may be preferable to a broader promise with uncertain staffing or supply. This is an operating recommendation to test, not a finding from the reported Rubis network.
Standards governance: continuity still needs verification
MobilityPlaza reports the termination of the Conexxus–IFSF Global Standards Development and Cross Licensing Agreement. It says both organisations retain rights to jointly developed standards and tools and may enhance them independently. That does not prove future compatibility, support periods or a required retailer migration. Standards-governance report
Operator analysis: request a version-specific roadmap
Ask suppliers which interface versions the installed system uses, who maintains them and how changes will be communicated. Preserve support and licensing terms. Avoid inferring that either organisation’s membership or a generic standards claim guarantees compatibility with every forecourt component.
For planned upgrades, require an acceptance test covering the actual equipment and transaction paths. Agree a supported fallback and an escalation owner for cross-supplier faults. Review the roadmap when a concrete specification or support change is announced, rather than inventing a technical consequence from a governance headline.
The two stories address different decisions: expansion of an operating network and ownership of standards work. Their connection is the need to verify scope and accountability. Neither report supplies a universal commercial uplift or establishes that existing forecourt software has suddenly become obsolete.
Editorial clarification — 8 September 2026
Clarified network totals versus new openings and removed speculative commercial benefits and technical consequences not established by the reports.